Monday, August 8, 2022

I’m Right 87.4% of the Time


I’m Right 87.4% of the Time

FAMILY UPDATE

As you may know, my daughter got her driver's license last week. We haven't seen her since. With her newfound freedom, she is out and about all the time. She goes shopping, goes out to eat, watches movies, visits friends...I fear I won't ever see her again.

We got the cats spayed and neutered. I never realized it but spaying a female cat is a much more serious surgery. She has to wear a cone on her head for ten days. She is not happy.


I was in my car the other day when I heard a commercial on the radio that got my attention:

"Most investors took a huge hit with the Coronavirus crash and now we are seeing signs of another crash. That pain, suffering, and financial loss don't have to happen, and we’ll show you how with a free demo of VantagePoint. Text the word FREE to 411411 to learn how we’ve applied artificial intelligence to protect your capital so you can navigate and thrive in volatile markets."

You will hear my extremely emotional response in a moment, but before that I need to point out: This is a criminal act. They are selling snake oil. They are scamming unsuspecting people.

These kinds of advertisements really start popping up when the markets are volatile.

I heard this on a reputable national station reaching untold numbers of listeners. I’ve listened to it several times since.

I don’t know exactly where to begin.

1. If I were to make these kinds of claims I would be stripped of my license. If you are registered with the SEC as a registered investment advisor you can NEVER—never, ever, ever—make claims like this. These yahoos get away with it because of a loophole in the system. They are not selling "investment advice;" they are selling software.

2. When was the huge crash with the Coronavirus exactly? The market was down a month and a half.

3. "The pain and suffering of financing loss." I see this tactic used quite often. These con men feed off of fear. It doesn’t matter if their "medicine" makes it much worse. They don’t care.

4. The part that completely floors me is where they say "We’ve applied artificial intelligence." What does that even mean? It certainly sounds exciting and cutting-edge. Maybe they do have some sort of algorithm they could use to help smooth out my portfolio, right?

No, they don’t.

Let’s think about this logically. If VantagePoint has this fancy software that will help you make all this money, why are they not using it for themselves? If their "artificial intelligence" can predict the movements of the market, wouldn’t the developers of this software be unfathomably wealthy? Why would they offer it to the public? They would make so much money by "navigating and thriving in volatile markets."

Next, I went to their website. Front and center was:

"Created by world-renowned trading software pioneer Louis B. Mendelsohn, VantagePoint forecasts Stocks, Futures, Forex, and ETFs with remarkable proven accuracy of up to 87.4%. Using artificial intelligence, VantagePoint’s patented Neural Network processes predict changes in market trend direction 1-3 days in advance. With this information, traders can confidently get in and out of trades at the optimal time. With nearly four decades and more than $10 million dollars of research and development invested, VantagePoint helps traders preserve their hard-earned capital and create real wealth."

This really gets me upset.

Making the claim of 87.4% accuracy is ridiculous. Again, I would probably go to jail if I ran around touting these claims. But these guys don’t go to jail. They are only selling software.

They use a "patented Neural Network process!" What could that possibly mean? I mean, seriously. It is just a bunch of fancy-sounding words strung together.

What is especially sad about these scams are all the unsuspecting investors out there losing all kinds of money day-trading using this worthless software. Not only are they paying a bunch of money for the software, but, by using the software, they lose even more. Remember, day trading doesn’t work over the long term.

Testimonials from the site:

Jeff S.

"In 2 months I was able to recoup my investment. I have since paid off my mortgage and car."

Sam A.

"I started using VantagePoint 6 months ago and my account has tripled!"

By now you clearly understand that this is a scam. I don’t understand how it can be advertised on national radio. I don’t even understand how this is legal.

What is the total cost for the VantagePoint Software system?

A mere $4,900.

Be Blessed,

Dave

Wednesday, August 3, 2022

The Oldest Old


The Oldest Old

FAMILY UPDATE Jesse does his morning workout with our dog in the pool. Then they relax and watch TV.

My daughter got her driver's license! She passed the first time. I failed my first time because I ran through the very first stop sign on the course.

Her first destination as a licensed driver? She went to Publix to buy donuts with her brothers.


I watched a couple of fascinating episodes of 60 Minutes recently. One covered how many Boomers are now taking on roommates to help defray the cost of their living expenses.

Many of my clients bristle at the idea. “Roommates in my 60’s and 70’s? Like on the Golden Girls? No way,” they say.

So I see them struggle to get by on their meager savings and Social Security.

This all goes back to the idea that having to ask for help shows some sort of weakness.

My wife fought breast cancer six years ago. As you can imagine, we learned a lot about a lot of facets of life. She had great doctors, and the surgeries were very difficult, but overall we made it through. That isn’t the part of the experience that surprised us the most.

What surprised us was all the help.

When you face a life-threatening illness (with four very young children) certain thoughts run through your mind. “How are we going to make it through this?"

We have some family down here, but they could only do so much. Somehow, we had to balance my wife's care, and the rest she needed, with the very real-life demands of raising four children.

Then something amazing happened.

People came out of the woodwork to help us. While some were friends before the illness, most were mere acquaintances. Maybe someone we met once or twice. Sometimes we were served by people who didn’t even know us, but knew we were in a time of need.

It was an incredible experience. You don’t know what support is there until you really need it.

So what’s my point? For whatever reason, the American culture has taught us to be completely self-reliant less you be a burden to society and those around you. In almost every culture throughout human history it was assumed that those in the community supported each other. It wasn’t a sign of weakness. It is simply how humans naturally organize societies.

There are people out there waiting to help. It gives them purpose and joy to be the helper.

So why not explore the option of having a roommate? If you are curious you can go to www.SilverNest.com. It is well-designed and useful. You don’t have to barely survive with lots of other people out there with limited resources as well. Not only does it save a ton of money, but many people also find they like having someone else around the house. Humans are social creatures.

The other episode reported on a fascinating study about the “oldest old”. Meaning, those in the ’90s and ’100s. The study followed 14,000 people. They were tracked throughout their lives, and it came away with some fascinating insights into how they are living so long.

Smoking obviously lowered life expectancy dramatically, and genes had a big part to play, but some of the other findings were more surprising.

They found that drinking between one and three cups of coffee a day actually increased life span.

And get ready for this…drinking 1-2 alcoholic beverages daily increased life expectancy by 1-2 years. When you’re done reading this article crack open a beer without shame. Your spouse might look at you strangely if you are reading this at seven in the morning.

The common belief is that red wine is healthy in moderation, but the study found that alcohol, in any form, was equally effective.

What about exercise? Not surprisingly it was an important indicator. Their findings revealed that forty-five minutes of exercise a day was ideal. Two hours was not better than forty-five minutes. You don’t need to kill yourself doing hardcore workouts, as moderate intensity yielded equally good results. You don’t need to do all forty-five minutes in a row either. It can be spread throughout the day.

Another interesting finding was that it was advantageous to be overweight. While being obese is always bad, being a bit overweight as you get older is an indicator of a longer life. You don’t want to be slim in your 90’s.

Non-physical activities: book clubs, socializing with friends, board games, all good. They lead to a longer life.

Vitamins and supplements are a hot topic, but the study found no correlation between taking vitamins and living longer.

If you want to watch the segments go to:

https://www.youtube.com/watch?v=wqKfL3z5yM4 (the oldest of the old)
https://www.youtube.com/watch?v=xB8CddeNG2c (silver nest roommates)

Be Blessed,

Dave

Monday, July 25, 2022


 COMMENTS

Is there any hope?

FAMILY UPDATE

My daughter had her sweet sixteen party this week. We hung out at the beach with her friends and even hired fire dancers. She is so beautiful and kind. I'm proud to be her Dad.

She is also going to take her driver's test this week. She doesn't need to parallel park or anything. But we've been hitting the roads (even the highway). I think she is fully prepared.

We have never given our six-month-old puppy a haircut We've been told that once he gets that first cut he will never be that soft again. I think it's time. I don't know how he even sees through the fluff.


Please read through the following statements and check the ones that apply to you. If you need more information on the topic I have linked past articles.

__ I look at my phone daily to see what the stock market is doing.

--- Whenever I hear someone on TV prognosticating, I say to myself, I better listen carefully. They are wearing a suit and have a nice haircut.

---I am afraid that the stock market will crash and my account will go to zero.

---This time is different. The world economy is more uncertain than at any other time in history.

---I am not going to spend any money from my retirement accounts unless I absolutely have to.

---Social Security is going insolvent. I cannot rely on it to be there throughout my retirement.

---While on Medicare, if I have a $300,000 medical bill from heart surgery it will bankrupt me. (Not true, the maximum out-of-pocket is $6700 a year)

---Unexpected retirement expenses will ruin my retirement.

---I know that my family will get along when they receive any sort of inheritance.

---I will only spend money from my retirement savings once retired unless I absolutely have to.

---I am too old to invest. I need to stick with CDs and savings accounts.

---I believe that I need to take my money out of my investments while this “blows over.”

---Buying physical gold off of a TV commercial is a great idea.

----If I spend enough time studying the market, I can make a lot of money trading in and out often.

---I will spend a lot more money in my 80’s and 90’s than in my 60’s and 70s.

__I go to as many “steak seminars” as possible.

---I’m afraid of being generous with my money because I might run out.

__I don’t have a will, power of attorney, and healthcare proxy.

---I am going to stop putting money into my 401k when the stock market is going down.

__I need a million dollars to even consider retiring.

---I know that taxes will eat me alive in retirement.

__I make sure to read any financial article with a scary title.

0-5 Great work! You accurately understand the complexities of retirement finance and planning.

5-10 Uh oh. You have some misconceptions that need to be addressed. It might be helpful to click on some of the links above to correct some of your thinking.

10-20 Danger! Danger! You may be living scared for no reason. You need to do some homework (and read some past articles) so that you don’t make significant mistakes with your retirement finances and lifestyle.

20-22 I’m afraid there’s no hope for you.

Be Blessed,

Dave

Monday, July 11, 2022

Inflation Will Destroy the World


 COMMENTS

Inflation Will Destroy the World


You may have heard the news.  The first half of this year had the worst market returns since 1970. That’s over 50 years!  Let’s take a look at how statistics can lie.  

In 1970, if you look at the whole year, the markets went up 3.56%.  That’s right.  The market completely recovered and then some by the end of the year. Don’t let the news trick you by twisting around data and history.

Does inflation have a direct correlation with lower stock market returns?  No.  Inflation does not mean the markets will go down.  The markets are fundamentally unknowable.  I know it is frustrating, but stock and bonds and illogical and unpredictable.  

So much of today’s market fluctuations are based on fear, greed, and speculation.  Companies are not showing lower profits.  Bonds are not defaulting on loans.  It’s all a game to see who can make the most money by guessing at market returns.  Long-term returns will remain the same.

See below for some perspective on the correlation between inflation and stock market returns.

Inflation  S&P Return  Year
14.4%         5.2%        1947
13.6%         31.7%      1980
11.3%         18.5%      1979
11.1%         -25.9%     1974
10.9%        19.2%       1942
10.3%        -4.7%        1981
9.1%          37.0%       1975
8.5%          -8.4%        1946
7.9%          23.7%        1951
7.7%          5.7%          1948
7.6%          6.5%          1978
6.5%         – 7.0%         1977
6.2%         -14.3%        1973
6.1%         20.4%         1982
6.0%         25.1%         1943
5.8%         3.6%           1970
5.7%         23.8%         1976

As you might notice:  There is no correlation.

What is up with all this recession talk?!  Sure the markets are having a tough time, and while the markets may drop even more, it has no bearing on your life.

You cannot listen to any news source lately without hearing warnings of a pending recession.  I’ve had several people in my office recently scared to death.

It is completely out of control.

Remember that the news will report on anything that will get and hold your attention. Stock market pullback? Big news!  Network executives are thrilled. It’s great for ratings, but it is terrible for you.

Why? It gives you the faulty perception that anyone and I mean anyone, can predict what will happen over the next days, months, and years.

Stay the course.  In a couple of years you won’t even remember this happened.

I’m sorry this article is so short this week.  My daughter is celebrating her Sweet 16, Grammy is coming into town, and we are very very busy.

Be Blessed,

Dave

Saturday, July 9, 2022

 I became a National Social Security Advisor to help equip pre-retirees with the understanding of how Social Security Benefits can be used to their maximum.

Everyone is unique and in different situations in life. Some are singles, many married or divorced and some even widowed. No matter your situation now or during retirement, learn the facts concerning your Social Security Benefits in a comprehensive relaxed setting, downtown Sarasota.


This FREE Social Security Timing Class is brought to you by National Social Security Advisor David Kennon in the PentHouse suite of Kane Plaza (held monthly). 

Our classes are strictly educational.

Things You Will Learn:

1. How your Full Retirement Age (FRA) affects your benefit payout.
2. What happens if your spouse is still working.
3. What if you still are or want to work part-time while claiming Social Security?
4. What if you are divorced or widowed?
5. How to maximize your Social Security benefits.
6. How inflation affects your benefits.
7. And much more!

Reservations are Required! Secure your seat at SarasotaClass.com

FREQUENTLY ASKED QUESTIONS:
Is there a cost to attend? No, there is no cost to attend.
Do I need to bring anything? No, just your smiling face.
Am I being pitched or sold anything? No. Our classes are for educational purposes only. The most common feedback we receive is how nice it is to attend a truly educational workshop with no pressure.

For more information go to SarasotaClass.com
Dates may update regularly

Tuesday, June 21, 2022

Temporary Losses and Permanent Gains


Temporary Losses and Permanent Gains

Family Update

We came back from Pittsburgh on Monday. I’m glad to be working in my office again instead of remotely. When we got back our puppy went completely nuts. I have never seen an animal express that kind of joy before. Every year we also measure all the kids. My middle son, Alex, just turned 12 and he grew more inches than anyone else. I would also like to point out that my wife is incredibly patient and kind. Do you want to know what it looks like to move a six-person family?


Should I Sell My Stocks?

Clearly, with the current economic situation, I am here to be the voice of reason. First of all, I want you to say to yourself (out loud if you so choose):  Markets temporarily go down and permanently go up.

As you can imagine, I’m getting the same questions over and over again. Here are the answers to some common ones:

Common Question #1

“Dave, I’m taking money from my portfolio each month. Do I need to stop that disbursement since the market is down?”

No. Remember, we are assuming an average of 5%. Did you get more money last year when the market was skyrocketing? No. You get what a diversified portfolio has averaged.

Common Question #2

This time is different. What do we do Dave?

This time isn’t different. I wrote an article about this about a month ago if you need to refresh your memory.

Common Question #3

“Do I need to worry?”

No.  This volatility has zero bearing on your long-term financial future.

Common Question #4

I’m too old to invest. This is all I have. What do I do?

It is very easy to remember when the stock market goes down, but most people do not remember that the Dow Jones was 21,000 during Covid and now it is at 30,000.

If you give into the fear, and put all of your money in cash, you are actually increasing your chances of running out of money. The most important variable when it comes to retirement planning is the fact that your money keeps working for you.

Common Question #5

“Should I get more conservative with my investments until this all blows over?”

No.

I’m going to give you cold, hard data that will debunk the concept that timing the markets in this situation might help.

I want you to know that I am not remotely worried. I’ve been through this before and it always ends the same way. Betting against innovation and progress is ALWAYS a mistake.

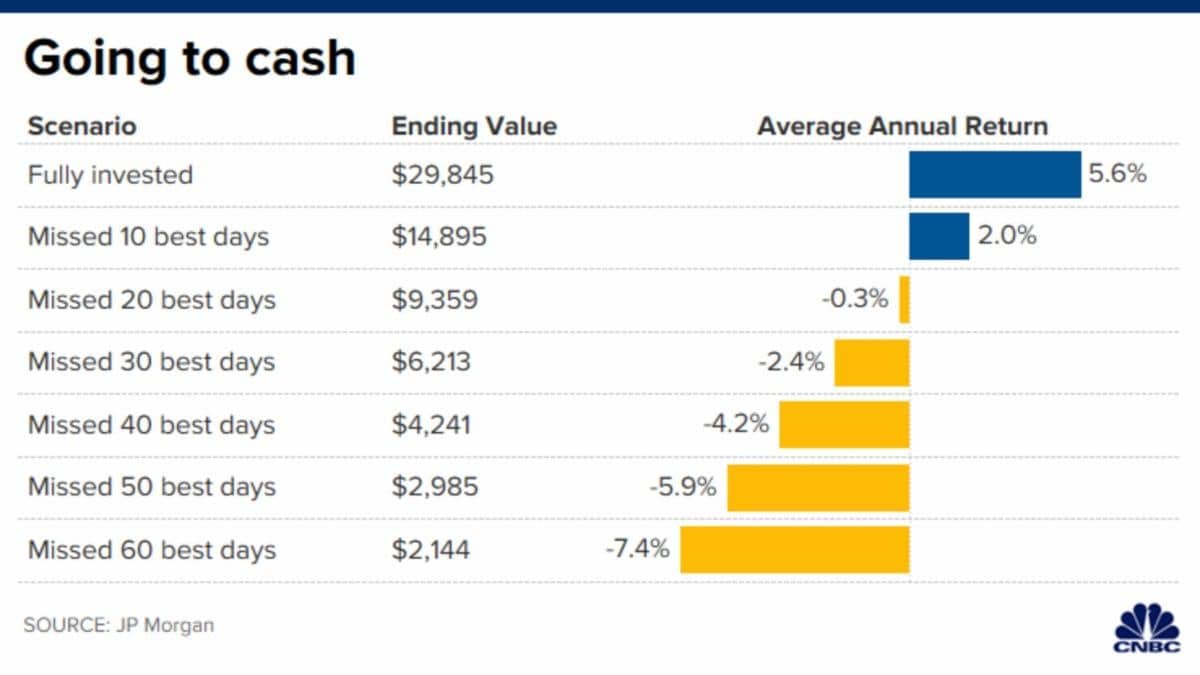
Here is a profoundly important chart.


What does this mean?

The chart is pointing out that, from 2000-2020, the stock market had averaged 5.6% per year. But if you missed the 10 best days, you would have lost two-thirds of the overall profits.

Think about that! Out of 7,300 days, missing the best ten, you decimated your long-term returns.

You cannot time the market.

I often hear, “I’m going to wait until things settle down.” When is that exactly? After the market has two amazing days, or three? Oops, you just messed up your whole life-long investment strategy.

You can do this!

Be Blessed,

Dave